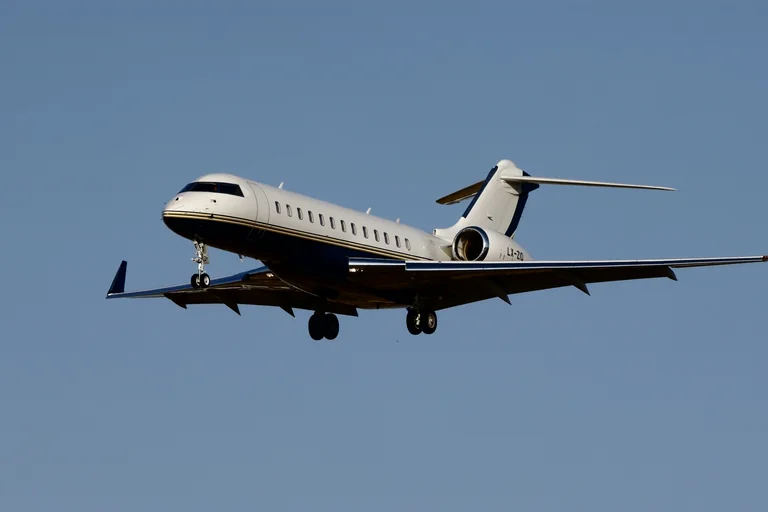
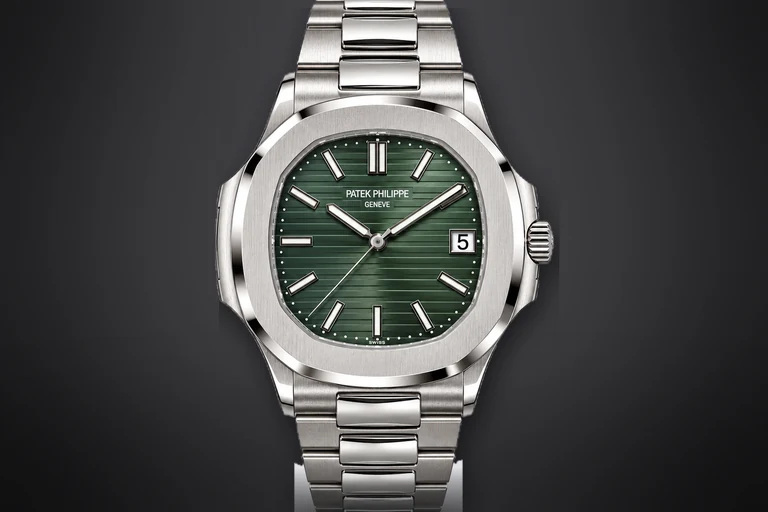
A last-minute aircraft is held for a limited window. A sought-after watch is available from a verified source, but only while the seller is prepared to reserve it. In these situations, payment is not an administrative detail. It is part of the execution. USDT versus wire transfers is therefore a practical decision about timing, documentation, risk and the counterparty’s ability to release the service or asset without delay.
For clients moving internationally, neither method is universally better. A wire transfer remains the established route for high-value commercial settlement. USDT can provide speed and flexibility across borders, particularly where banking cut-offs, public holidays or multiple currencies would otherwise slow a decision. The right choice depends on the transaction, the jurisdictions involved and how quickly funds must be confirmed.
USDT versus wire transfers: the operational difference
A bank wire is an instruction sent through the banking system. Its strength is familiarity. Aircraft operators, yacht brokers, hotels, dealers and professional service providers understand it, and the accompanying records are generally straightforward for accounting, audit and compliance teams.
Its limitation is timing. A wire initiated after a bank’s cut-off may not move until the following business day. Intermediary banks can hold or query funds, especially where the payment crosses borders, includes an unfamiliar beneficiary or originates from a new corporate structure. A payment may be sent, but not yet cleared or credited to the recipient’s account. For a charter departing within hours, that distinction matters.
USDT is a stablecoin designed to track the US dollar. Once a transaction has been sent to the correct wallet address and receives the required network confirmations, it can usually be verified far more quickly than an international wire. This can be useful when a client is confirming a late aircraft repositioning, securing a villa during peak season or settling a watch purchase while banks are closed in one or more relevant jurisdictions.
Speed is not the only difference. A wire transfer travels through a regulated banking relationship and may offer established recall or investigation processes if something is wrong. A USDT transaction is generally irreversible once confirmed. Sending funds to an incorrect wallet address, choosing an unsupported network or acting on fraudulent payment instructions can create an immediate and potentially permanent loss. The operational discipline around USDT must therefore be higher, not lower.
When USDT is the stronger option
USDT is often most useful when time is the pressure point. Consider a principal in Dubai confirming an aircraft for a morning departure from Farnborough, while the operator’s settlement account is in Europe and the booking is being finalised outside normal banking hours. If all parties have completed the necessary checks and the operator accepts stablecoin settlement, USDT can make funding visible quickly enough to protect the aircraft release.
It also suits clients whose liquidity is already held in digital assets. Converting crypto into fiat purely to make a payment can add exchange timing, banking friction and unnecessary administration. Direct settlement in an accepted stablecoin may be cleaner, provided the recipient, network and reference process have been agreed in advance.
For multi-jurisdictional arrangements, USDT can remove some of the delays associated with currency conversion and correspondent banking. That does not remove compliance obligations. Reputable providers will still need to understand the source of funds, the identity of the paying party and the purpose of the transaction. For substantial payments, wallet screening and transaction records should be expected.
The practical advantage is control over timing. A client does not need to wait for a bank in a different time zone to open before evidence of payment can be produced. That can be decisive where access is scarce and the supplier will not hold an asset without cleared funds.
The conditions that need to be right
USDT works best when the payment route is confirmed before funds move. The recipient should specify the accepted token and blockchain network. USDT exists on more than one network, and an address alone does not make the instruction complete. The payer should independently verify the address through a trusted channel, ideally with a test transfer where the value and timetable allow it.
The commercial terms also need to be clear. Is the quoted price fixed in pounds, dollars or euros? At what point is the exchange rate set if conversion is required? How many confirmations constitute cleared payment? Who bears network fees? These details are unglamorous, but they prevent avoidable disagreement when an aircraft, hotel or asset is being released.
Where wire transfers remain the better choice
For planned travel and purchases with adequate lead time, a bank wire is often the simplest answer. It is familiar to institutional suppliers, aligns well with corporate treasury processes and gives a conventional audit trail from the payer’s account to the beneficiary’s account.
A wire can be preferable where the supplier does not accept digital assets directly, where the buyer requires settlement from a named company account, or where a family office needs formal payment controls and multiple approvals. It may also be the more comfortable route for a transaction involving a new counterparty, particularly when the buyer wants the additional protections and investigation procedures available within banking channels.
For rare watches, wires are still common because provenance, condition, title and delivery terms often require close attention alongside the payment. Payment speed is useful, but it should not outrun verification. A rapid stablecoin settlement does not compensate for an incomplete serial check, unclear ownership history or poorly documented export position.
The same principle applies to private aviation. An operator may be able to accept a fast USDT payment, but the charter agreement, passenger details, routing permissions, insurance requirements and catering brief still need to be properly confirmed. Payment can remove a delay. It cannot replace operational due diligence.
Cost, privacy and control
Wire fees vary. A domestic transfer may be inexpensive, while an international payment can incur sending charges, receiving fees, intermediary deductions and foreign-exchange spreads. The final amount received may be lower than the amount sent unless the payment instruction and fee allocation have been set correctly.
USDT transaction fees are typically visible before sending, but they can vary by network and market conditions. The more significant cost may be conversion: moving from another asset into USDT, or converting USDT into fiat at the receiving end. A client should compare the full settlement cost rather than focusing on the transfer fee alone.
Privacy requires similar realism. Neither route is anonymous when arranged properly. Banks maintain records, and regulated suppliers may request supporting documents. Blockchain transactions are visible on public ledgers, while wallet ownership may be linked to identity through exchanges, compliance providers or transaction analysis. For principals who value discretion, the objective should be controlled disclosure to the necessary parties, not the illusion of invisibility.
Control comes from process. For a wire, confirm beneficiary details verbally using an established contact, especially if banking instructions have changed. For USDT, verify the wallet address and network through a second channel, document the agreed value, and retain the transaction hash and confirmations. In both cases, do not rely on an email change of payment details without independent verification.
A practical approach for high-value arrangements
The best payment method is often determined before the request becomes urgent. A client who expects to charter frequently, acquire collectible assets or make bookings across time zones should establish approved payment routes in advance. This means completing onboarding early, agreeing which entities can pay, recording trusted beneficiary details and deciding whether stablecoin settlement is available for specific services.
For transactions with a hard deadline, the payment conversation should begin alongside the sourcing conversation. If an aircraft is being held, ask when it will be released, what evidence of payment the operator accepts and whether a deposit can secure the slot while final funds clear. If a watch is located, confirm whether the price is net of all fees, what documentation will accompany it and the point at which title passes.
A boutique operator should be able to coordinate these details through one contact rather than sending the client between a broker, finance department, dealer and concierge desk. The 0.1% Group can arrange crypto-enabled settlement where suitable, while keeping the commercial and operational sequence clear: availability first, verification second, payment instruction confirmed, then release.
The decision is about the brief, not the novelty
USDT is not a replacement for wire transfers in every circumstance. It is a valuable settlement tool when speed, global availability and crypto-held liquidity are central to the brief. Wires remain the dependable choice when institutional familiarity, conventional controls and planned settlement matter more than immediate confirmation.
For a departure tomorrow, a rare asset held briefly, or an itinerary spanning several jurisdictions, ask one question early: what payment route gives the supplier verified funds in time without compromising control? Once that is answered, the rest of the arrangement can move with purpose.